Original work by The Thorium Network. Support us on [Patreon]. Licensed CC BY 4.0—reproduction permitted with attribution.
The global nuclear industry is entering a period of structural divergence.
China, Russia, India, South Korea and several newer nuclear states are expanding reactor fleets, supply chains and technical work forces. The United States, Canada and much of Western Europe still operate large nuclear fleets, but many of those reactors were built during the expansion wave of the 1960s–1990s. Their future depends increasingly on life extensions rather than replacement.
This creates a powerful asymmetry: the West continues to generate substantial nuclear electricity from old assets while much of Eurasia builds new capacity.
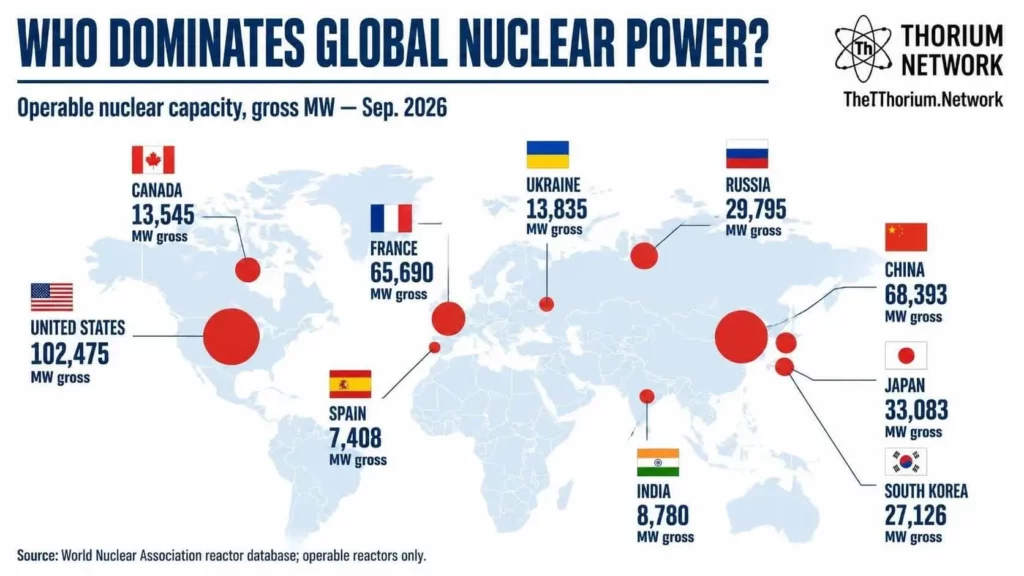
The model of this article assumes that Western governments do not achieve a sustained nuclear construction revival. Existing reactors may receive selected life extensions, but there is no large-scale replacement program comparable to the original build-out. China, Russia, India and other emerging nuclear states, by contrast, continue building at historically significant rates.
This is a predictive scenario model with substantive assumptions. Use it to plan your future. Not to predict it.
The central finding
Under this scenario:
- Western nuclear capacity declines from approximately 220 GW in 2026 to near zero by 2100.
- BRICS+ nuclear capacity rises from approximately 110 GW to about 1,650 GW.
- Global nuclear capacity increases from roughly 420 GW to approximately 1,970 GW.
- Annual nuclear generation rises from about 3,100 TWh to nearly 14,700 TWh, assuming an average global capacity factor of 85%.
- China becomes the dominant nuclear power in the 2030s.
- India becomes the second-largest long-term growth market.
- Russia remains both a major domestic operator and the largest international nuclear technology exporter.
- Japan and South Korea retain substantial technical capability, while Japan’s trajectory depends heavily on reactor restarts and replacement construction.
The model is deliberately more pessimistic about Western construction than mainstream energy-transition scenarios. It assumes that political support, industrial capacity and public acceptance remain insufficient to produce a sustained Western build out, stifled by legacy coal, oil and gas interests and their focus on maintaining their dwindling profit base.
1. The existing Western fleet is old
The Western nuclear fleet is not uniformly obsolete. Many reactors can operate safely beyond their original design and licensing periods if they receive major inspections, component replacements and regulatory approval.
However, age still matters.
The average age of the United States reactor fleet was approximately 44 years in 2026. Most U.S. reactors entered service between the late 1960s and early 1990s. The newest U.S. reactors are Vogtle 3 and 4, which entered commercial service in 2023 and 2024. Before them, the United States had gone more than 30 years without completing a new commercial reactor.
U.S. reactors receive an initial 40-year operating license. They may then receive a 20-year extension to 60 years, followed by a second 20-year extension to 80 years. An 80-year operating life is therefore not automatic; it requires additional safety analysis, environmental review, ageing-management programs and capital investment.
As of the latest available licensing data, a relatively small group of U.S. reactors had received approval to operate for 80 years. The approved units include reactors at Turkey Point, Peach Bottom, Surry, North Anna, Monticello, Oconee, Browns Ferry, Dresden, St. Lucie, Robinson and Hatch. That is significant, but it represents only a portion of the national fleet.
There is no established commercial pathway in the United States for operating the current light-water reactor fleet routinely to 100 years. A few plants may eventually be studied for operation beyond 80 years, but that would involve another level of engineering review and substantial replacement of ageing systems. It should not be treated as the normal future of the fleet.
Approximate age structure of Western nuclear assets
| Asset age in 2026 | Approximate condition | Likely outcome |
|---|---|---|
| Under 20 years | New or relatively modern | Likely to operate into the 2070s or later |
| 20–40 years | Mature fleet | Likely to require major refurbishment |
| 40–60 years | Old operating fleet | Dependent on licence renewal and economics |
| 60–80 years | Extended operation | Technically possible for selected units |
| Over 80 years | Beyond current normal licensing framework | Retirement or exceptional life-extension decision |
The issue is not that a reactor reaches a magical age at which it must shut down. The issue is that every additional decade requires more expensive inspection, replacement of components, updated safety analysis and continued political commitment.
2. Western life extensions are important—but they are not a replacement program
A life extension preserves capacity. It does not create a new industrial base.
Extending an existing reactor may require:
- Steam-generator replacement
- Reactor-vessel inspection
- Reactor-head replacement
- Turbine and generator refurbishment
- New control and instrumentation systems
- Cooling-system upgrades
- Seismic reassessment
- Fire-protection improvements
- Digital safety-system modernisation
- Spent-fuel and radioactive-waste infrastructure
- New training and qualification programs
These investments can be justified because the plant already has grid connections, operating staff, fuel contracts and a regulatory history. A new reactor must establish all of those systems from scratch.
The Western nuclear industry’s most serious weakness is therefore not simply the age of its reactors. It is the failure to maintain a continuous construction pipeline.
The United States currently operates one of the world’s largest nuclear fleets, but its latest large reactors were built after a long interruption. Vogtle 3 and 4 demonstrated that the country can still complete a reactor, but the project took more than a decade from construction start to commercial operation and experienced major delays and cost escalation.
The Energy Information Administration has reported that the United States has 94 operating reactors, while most of the country’s fleet was built between 1967 and 1990. Current international reactor-construction data show no U.S. large reactor under construction, despite a large number of proposed projects.
That is critical:
- Operating: producing electricity now
- Licensed: legally authorised to operate
- Planned: some level of policy or corporate commitment
- Proposed: an idea, study or preliminary site concept
- Under construction: actual civil works have begun
Only the last category creates near-term replacement capacity.
3. Western construction capacity has become intermittent
France provides the clearest example of a country with enormous nuclear expertise but a disrupted construction pipeline.
France built most of its nuclear fleet rapidly during the 1970s and 1980s, using a largely standardised reactor design. That fleet still generates the majority of the country’s nuclear electricity. However, France then went decades without completing a new large reactor at home. Construction of the Flamanville 3 reactor began in 2007, but it did not connect to the national grid until 2024—a 17-year construction process that highlighted the difficulty of restarting a dormant nuclear-build program.
The result is a familiar pattern:
- A country constructs a large fleet rapidly.
- Construction stops.
- Suppliers, engineers and specialised contractors retire or leave.
- Regulatory and design knowledge becomes less current.
- The next reactor becomes slower and more expensive.
- The industry loses confidence and political support.
- Existing reactors are extended because replacement projects are difficult.
The same pattern appeared in the United States, the United Kingdom and parts of Western Europe. The United Kingdom is still pursuing new nuclear projects, and France has announced additional construction ambitions. But announced projects are not equivalent to operating capacity.
The International Energy Agency has described the current nuclear revival as highly uneven. It reports that advanced-economy fleets are older than fleets elsewhere, while China accounts for roughly half of the nuclear capacity under construction. The IEA also found that, among reactors beginning construction since 2017, Chinese and Russian clearly designs dominate.
4. The workforce problem is real, “no graduates”
The Western nuclear workforce is literally producing fewer graduates. Universities still graduate nuclear engineers, radiation-protection specialists, mechanical engineers, electrical engineers, chemists and operators. But at reducing rates.
The problem is scale, age distribution and experience.
The United States nuclear sector employed approximately 68,008 workers in 2023, including fuel-cycle and electric-generation employment. Utilities accounted for roughly 41,000 positions. The U.S. Department of Energy reported that 60% of nuclear workers were between ages 30 and 54, while the industry had 23% fewer workers under 30 than the overall energy workforce. Around 90% of professional and business-service employers reported difficulty finding qualified workers. U.S. Department of Energy
That creates three separate risks:
Retirement risk
A reactor is operated through procedures, maintenance practices and engineering judgements that are not fully captured in textbooks. Much of that expertise is held by people who joined the industry during the original build out.
As those workers retire, companies must replace both the person and the experience base. A new graduate may understand reactor physics but still require years of supervised experience before becoming qualified for high-responsibility plant positions.
Training-pipeline risk
A new reactor program requires far more than reactor operators. It needs:
- Nuclear engineers
- Welders and pipefitters
- Quality-assurance inspectors
- Nuclear safety analysts
- Radiation-protection specialists
- Control-room operators
- Heavy-forging specialists
- Nuclear lawyers and regulators
- Project managers
- Fuel-cycle specialists
- Waste-management professionals
- Skilled construction supervisors
The OECD Nuclear Energy Agency has repeatedly identified ageing and retirement as major human-resource risks for countries maintaining or expanding nuclear programs.
Project-cycle risk
A nuclear industry that builds one reactor every few decades cannot maintain the same workforce as an industry building several units every year.
China, Russia and South Korea benefit from repeated construction. Their engineers, suppliers and contractors move from one project to the next. A Western team may complete a major reactor project and then have no comparable project for many years.
That difference compounds over time.
5. BRICS+ is building the industrial base the West is losing
The term BRICS+ has become politically fluid. Its expanded membership includes Brazil, Russia, India, China, South Africa, Egypt, Ethiopia, Iran, the United Arab Emirates and Indonesia, with the exact status of some members and invited states changing over time.
The nuclear capability of this group is concentrated in a smaller subset:
- China
- Russia
- India
- South Africa
- Brazil
- Iran
- United Arab Emirates
- Egypt, which is building its first nuclear plant ready by 2028
The group also has connections to other major nuclear-building states, including Pakistan and Türkiye, although those countries are not treated as BRICS members in this model.
Current and projected BRICS+ nuclear capacity
| Country | Approx. operating capacity, 2026 | Predictive capacity, 2050 | Predictive capacity, 2100 |
|---|---|---|---|
| China | 64 GW | 300 GW | 950 GW |
| Russia | 28 GW | 75 GW | 180 GW |
| India | 8 GW | 80 GW | 400 GW |
| United Arab Emirates | 5.6 GW | 6 GW | 12 GW |
| South Africa | 2 GW | 4 GW | 20 GW |
| Brazil | 2 GW | 5 GW | 25 GW |
| Iran | 1 GW | 3 GW | 15 GW |
| Egypt | 0 GW | 5 GW | 20 GW |
| Indonesia | 0 GW | 0–5 GW | 20 GW |
| Ethiopia | 0 GW | 0 GW | 5 GW |
| BRICS+ subtotal | approximately 111 GW | approximately 483 GW | approximately 1,647 GW |
These figures are a high-growth scenario based on current construction momentum, announced programs and the assumption that electricity demand continues to rise in developing economies.
China is the anchor of the projection. It operates roughly 64 reactors and has approximately 38 reactors under construction, with more planned. India has a much smaller installed base but a large long-term target and an expanding domestic reactor program. Russia combines domestic construction with a powerful export business.
The IEA reported that in 2025 China, India and Russia each completed new reactor capacity, while nine of ten global construction starts occurred in China. It also reported that approximately 94% of reactors beginning construction during the previous decade used Chinese or Russian designs. iea.org
The World Nuclear Association lists approximately 80 reactors under construction worldwide, with roughly half of the capacity in China. It also lists more than 120 additional reactors as planned, most of them in Asia and other emerging markets.
6. Russian-built capacity will extend beyond Russia
Russia’s influence cannot be measured only by reactors physically located inside Russia.
Rosatom supplies:
- Reactor designs
- Engineering services
- Fuel
- Enrichment
- Training
- Long-term maintenance
- Financing arrangements
- Waste and fuel-cycle services
Russian-designed reactors are being built or proposed in countries including Türkiye, Egypt, Bangladesh, Iran and others. A reactor built in Egypt counts as Egyptian generating capacity, but it also expands Russia’s industrial influence and export ecosystem.
China is following a similar path, although its overseas nuclear-export position is not yet as extensive as Russia’s. Chinese reactor designs are increasingly standardised, and domestic construction gives Chinese suppliers a large reference base.
This is one of the most important differences between a declining industrial system and an expanding one:
- A declining system extends its existing plants.
- An expanding system builds plants at home and exports the entire technology package abroad.
7. The 74-year predictive model: 2026–2100
The following model divides nuclear capacity into three categories:
- Western capacity: United States, Canada, Western Europe, the United Kingdom and associated mature nuclear economies.
- BRICS+ capacity: The BRICS+ countries with existing or developing nuclear programs.
- Other non-Western capacity: Japan, South Korea, Ukraine, Pakistan, Türkiye and other nuclear states outside the two groups.
The model assumes:
- No sustained Western nuclear construction revival
- Selected Western reactors receive 60- or 80-year extensions
- Western reactor retirements accelerate after 2040
- China maintains a high construction rate through mid-century
- India accelerates construction after 2035
- Russia maintains both domestic construction and export activity
- Japan restarts most technically viable reactors but builds only moderately
- South Korea continues a steady replacement and export program
- Global nuclear capacity factors average approximately 85%
Installed nuclear capacity and estimated generation
| Year | Western capacity | BRICS+ capacity | Other non-Western capacity | Global capacity | Approx. annual generation at 85% capacity factor |
|---|---|---|---|---|---|
| 2026 | 220 GW | 110 GW | 90 GW | 420 GW | 3,130 TWh |
| 2030 | 205 GW | 170 GW | 105 GW | 480 GW | 3,580 TWh |
| 2040 | 180 GW | 300 GW | 140 GW | 620 GW | 4,620 TWh |
| 2050 | 145 GW | 500 GW | 175 GW | 820 GW | 6,110 TWh |
| 2060 | 100 GW | 750 GW | 210 GW | 1,060 GW | 7,950 TWh |
| 2070 | 60 GW | 1,000 GW | 250 GW | 1,310 GW | 9,740 TWh |
| 2080 | 30 GW | 1,250 GW | 280 GW | 1,560 GW | 11,610 TWh |
| 2090 | 10 GW | 1,450 GW | 300 GW | 1,760 GW | 13,100 TWh |
| 2100 | 0 GW | 1,650 GW | 320 GW | 1,970 GW | 14,660 TWh |
The generation estimate uses:
At an 85% capacity factor, each 1 GW of nuclear capacity produces approximately 7.45 TWh per year.
This model does not consider other power sources. Wind, solar, hydroelectricity, gas, coal, storage and transmission will also expand or decline. The focus is the amount of electricity generated by nuclear power and the,point is that it can rise substantially even while the Western nuclear industry contracts.
8. Western retirement schedule
The model assumes that most current Western reactors fall into one of four categories:
| Period | Main Western nuclear event |
|---|---|
| 2026–2035 | Life extensions, restarts and completion of already-committed projects |
| 2035–2045 | Increasing retirement of reactors that reach 60 years |
| 2045–2060 | Large retirement wave as many reactors reach 70–80 years |
| 2060–2080 | Final operation of selected exceptionally extended units |
| 2080–2100 | Decommissioning, waste management and site remediation dominate |
The most important point is that retirement is not a single event. Nuclear capacity tends to decline in waves because many countries built fleets in concentrated periods.
France built much of its fleet between the mid-1970s and early 1990s. The United States also built most of its capacity between 1967 and 1990. This creates a retirement bulge: a large number of reactors eventually reach similar age thresholds at roughly the same time.
If replacements are not started 10–20 years in advance, a country cannot simply “replace” the fleet when it reaches retirement age. Nuclear construction timelines make that impossible.
9. A crumbling power infrastructure
The Western problem is broader than nuclear reactors.
Nuclear plants are connected to:
- High-voltage transmission networks
- Regional control systems
- Cooling-water infrastructure
- Rail and heavy-haul logistics
- Specialised machine shops
- Nuclear fuel supply chains
- Emergency-response systems
- Universities and training institutions
- Regulatory agencies
- Waste-storage facilities
When the nuclear fleet contracts, the surrounding infrastructure also loses scale.
A shrinking fleet can mean:
- Fewer apprenticeships
- Fewer reactor projects for contractors
- Less demand for nuclear-grade forgings
- Fewer university nuclear programs
- More expensive regulator staffing
- More dependence on foreign fuel and components
- Loss of domestic design expertise
- Higher costs for the remaining plants
- Greater difficulty restarting the industry later
This is why a temporary construction pause can become a long-term industrial decline. The capability is not preserved simply because a few reactors continue operating.
10. Oil and coal interests: a forever strong influence
It is a fact that fossil-fuel interests influence energy policy. Oil, gas and coal companies have financial stakes in maintaining demand for their products, and fossil-fuel industries employ large workforces and possess significant political influence.
The entire Western nuclear stagnation can be assigned entirely to private families making money from oil and coal.
There are other factors too. Such as:
- Nuclear construction cost overruns from inexperienced teams
- High interest rates
- Long permitting timelines
- Public opposition maintained through oil funded campaigns
- Accident risk perception
- Waste-disposal disputes
- Utility deregulation
- Competition from cheap natural gas
- Renewable subsidies and rapid solar-cost declines
- Local opposition to new transmission lines
- Loss of skilled construction capacity
- Political changes after major accidents
- Difficulty financing projects that take a decade to complete
Fossil-fuel interests reinforce these barriers, and can be tied to all elements. A fragmented political system, weak project execution and inconsistent policy are also part of the collective western problem.
The observable fact is: the West has not built replacement reactors at the rate required to preserve its existing nuclear share.
11. Why global nuclear generation can rise while Western nuclear declines
The Western decline does not necessarily imply a global nuclear decline.
China, India and other emerging economies have three structural advantages:
- Growing electricity demand .They need much more electricity for industrialisation, urbanisation, cooling, transport and digital infrastructure.
- Centralised decision-making. Large infrastructure projects can often be approved and financed through state-directed systems more quickly than in fragmented liberal markets.
- Continuous construction. Repeated projects preserve engineering teams, manufacturing capacity and regulatory experience.
This creates a compounding effect. A country that builds ten reactors learns faster than a country that builds one reactor every 20 years. The cost of standardisation, training and supply-chain development is spread across a larger pipeline.
The IEA estimates that China’s installed nuclear capacity more than triples to mid-century in its policy-based scenario, while emerging and developing economies account for most of the expected growth. It also notes that advanced-economy nuclear fleets are older and that new construction has been affected by delays and cost overruns.
12. The likely geopolitical result by 2100
If this scenario is broadly correct, nuclear power becomes entirely associated with Asian and Eurasian industrial systems.
By 2100:
- China controls the largest domestic nuclear fleet.
- India controls the second-largest growth market.
- Russia remains a major reactor and fuel supplier.
- South Korea remains a sophisticated reactor exporter.
- Japan retains high technical competence but operates a smaller and older fleet than China or India.
- Western countries retain ever decaying nuclear knowledge in universities, laboratories and selected companies but no longer dominate deployment.
- Much of the world’s new reactor capacity uses Chinese, Russian, Indian or South Korean designs.
- Western countries become customers, regulators and operators rather than the main builders.
This becomes a technological defeat. Western countries no longer lead in advanced reactor research, safety analysis, fuel innovation or nuclear medicine. They won’t have the machines. Leadership in research will shift eastwards also.
Conclusion
The central story is not that Western reactors suddenly fail. It is that they gradually age out while the industrial system needed to replace them remains too small, too slow and too politically inconsistent.
The West can extend many reactors to 60 years and selected reactors to 80 years. That will preserve substantial generation through the 2030s and 2040s. It will not, by itself, create a replacement fleet for the second half of the century.
China, Russia, India and other nuclear-building states are moving in the opposite direction. They are building reactors, training workers, expanding supply chains and creating repeatable construction systems.
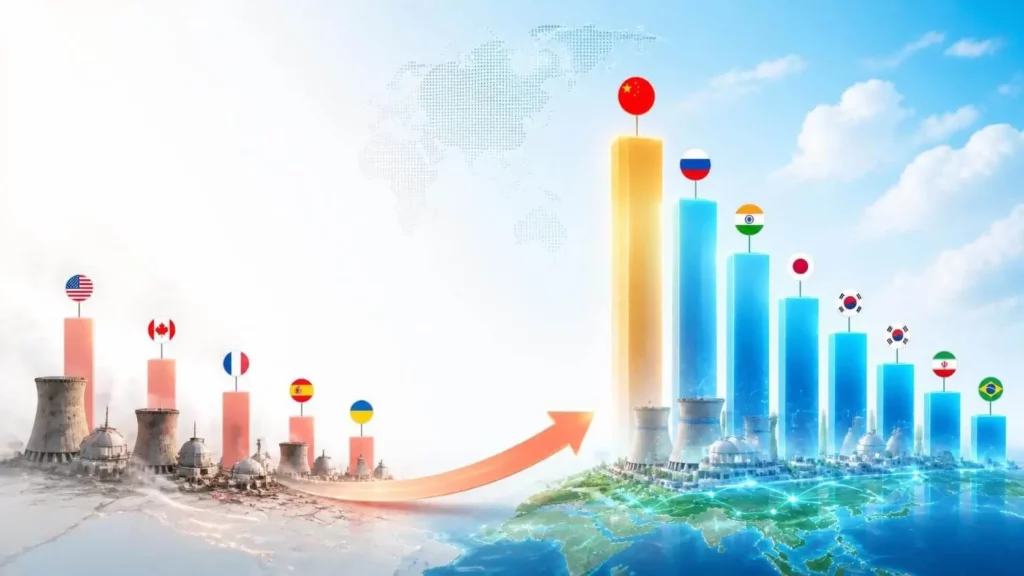
Under the predictive model presented here, Western nuclear capacity falls by approximately 220 GW between 2026 and 2100, while BRICS+ capacity rises by approximately 1,540 GW. Global nuclear generation increases because the additions in Asia and the wider BRICS+ sphere overwhelm Western retirements.
The likely result is a historic transfer of nuclear industrial power:
The West owns much of the ageing fleet. Eurasia builds the replacement fleet.